

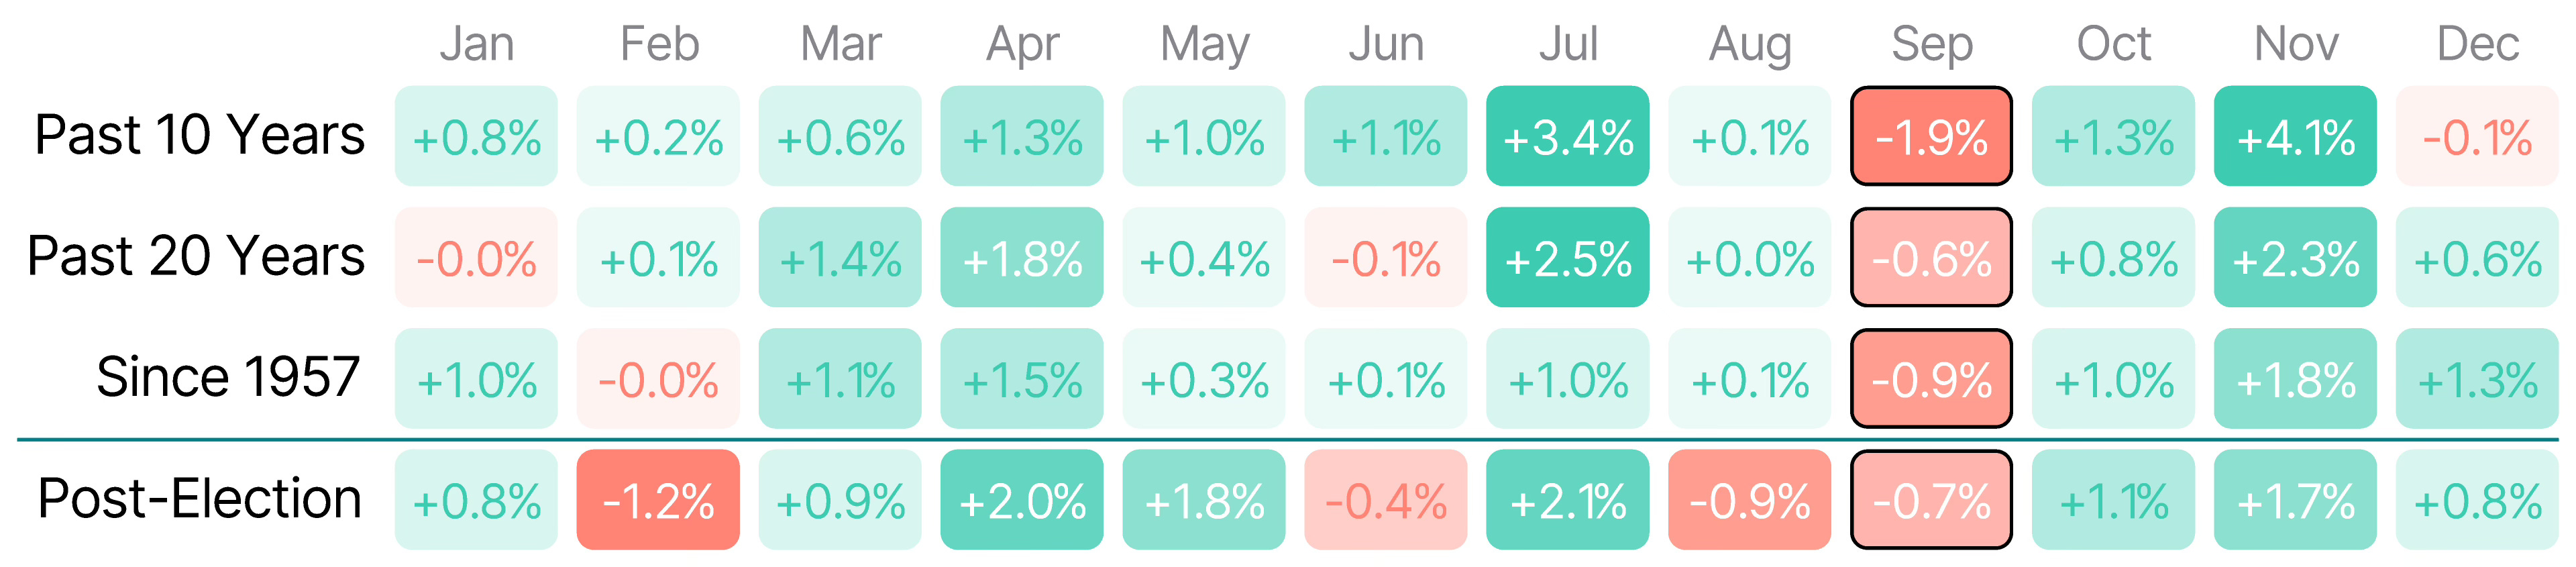
With 9 of 11 S&P 500 sectors finishing higher in August — typically one of the weakest months of the year — it’s worth questioning how much weight we should really give to seasonality charts.
August just proved that markets don’t need to follow the calendar, especially when bullish momentum is intact.
Now, September has the reputation of being the worst month of the year, and that has been true more often than not in recent times. But since the market has already shrugged off June’s and August’s post-election seasonality trends, there’s a good chance strong momentum will beat seasonality again this time.
Of course, whether Powell cuts rates mid-month will have its own impact on markets. But what’s not flashing caution right now are a few of the ratios we like to track, including:
Discretionary vs Staples (cap- and equal-weighted)
High Beta vs Low Volatility
Small Caps vs Large Caps
High Yield vs Treasuries
Ethereum vs Bitcoin
Now, looking at our go-to risk appetite check — Discretionary vs Staples — and listening to the best risk sniffers in the market — credit investors — one could argue that growth is actually reaccelerating.
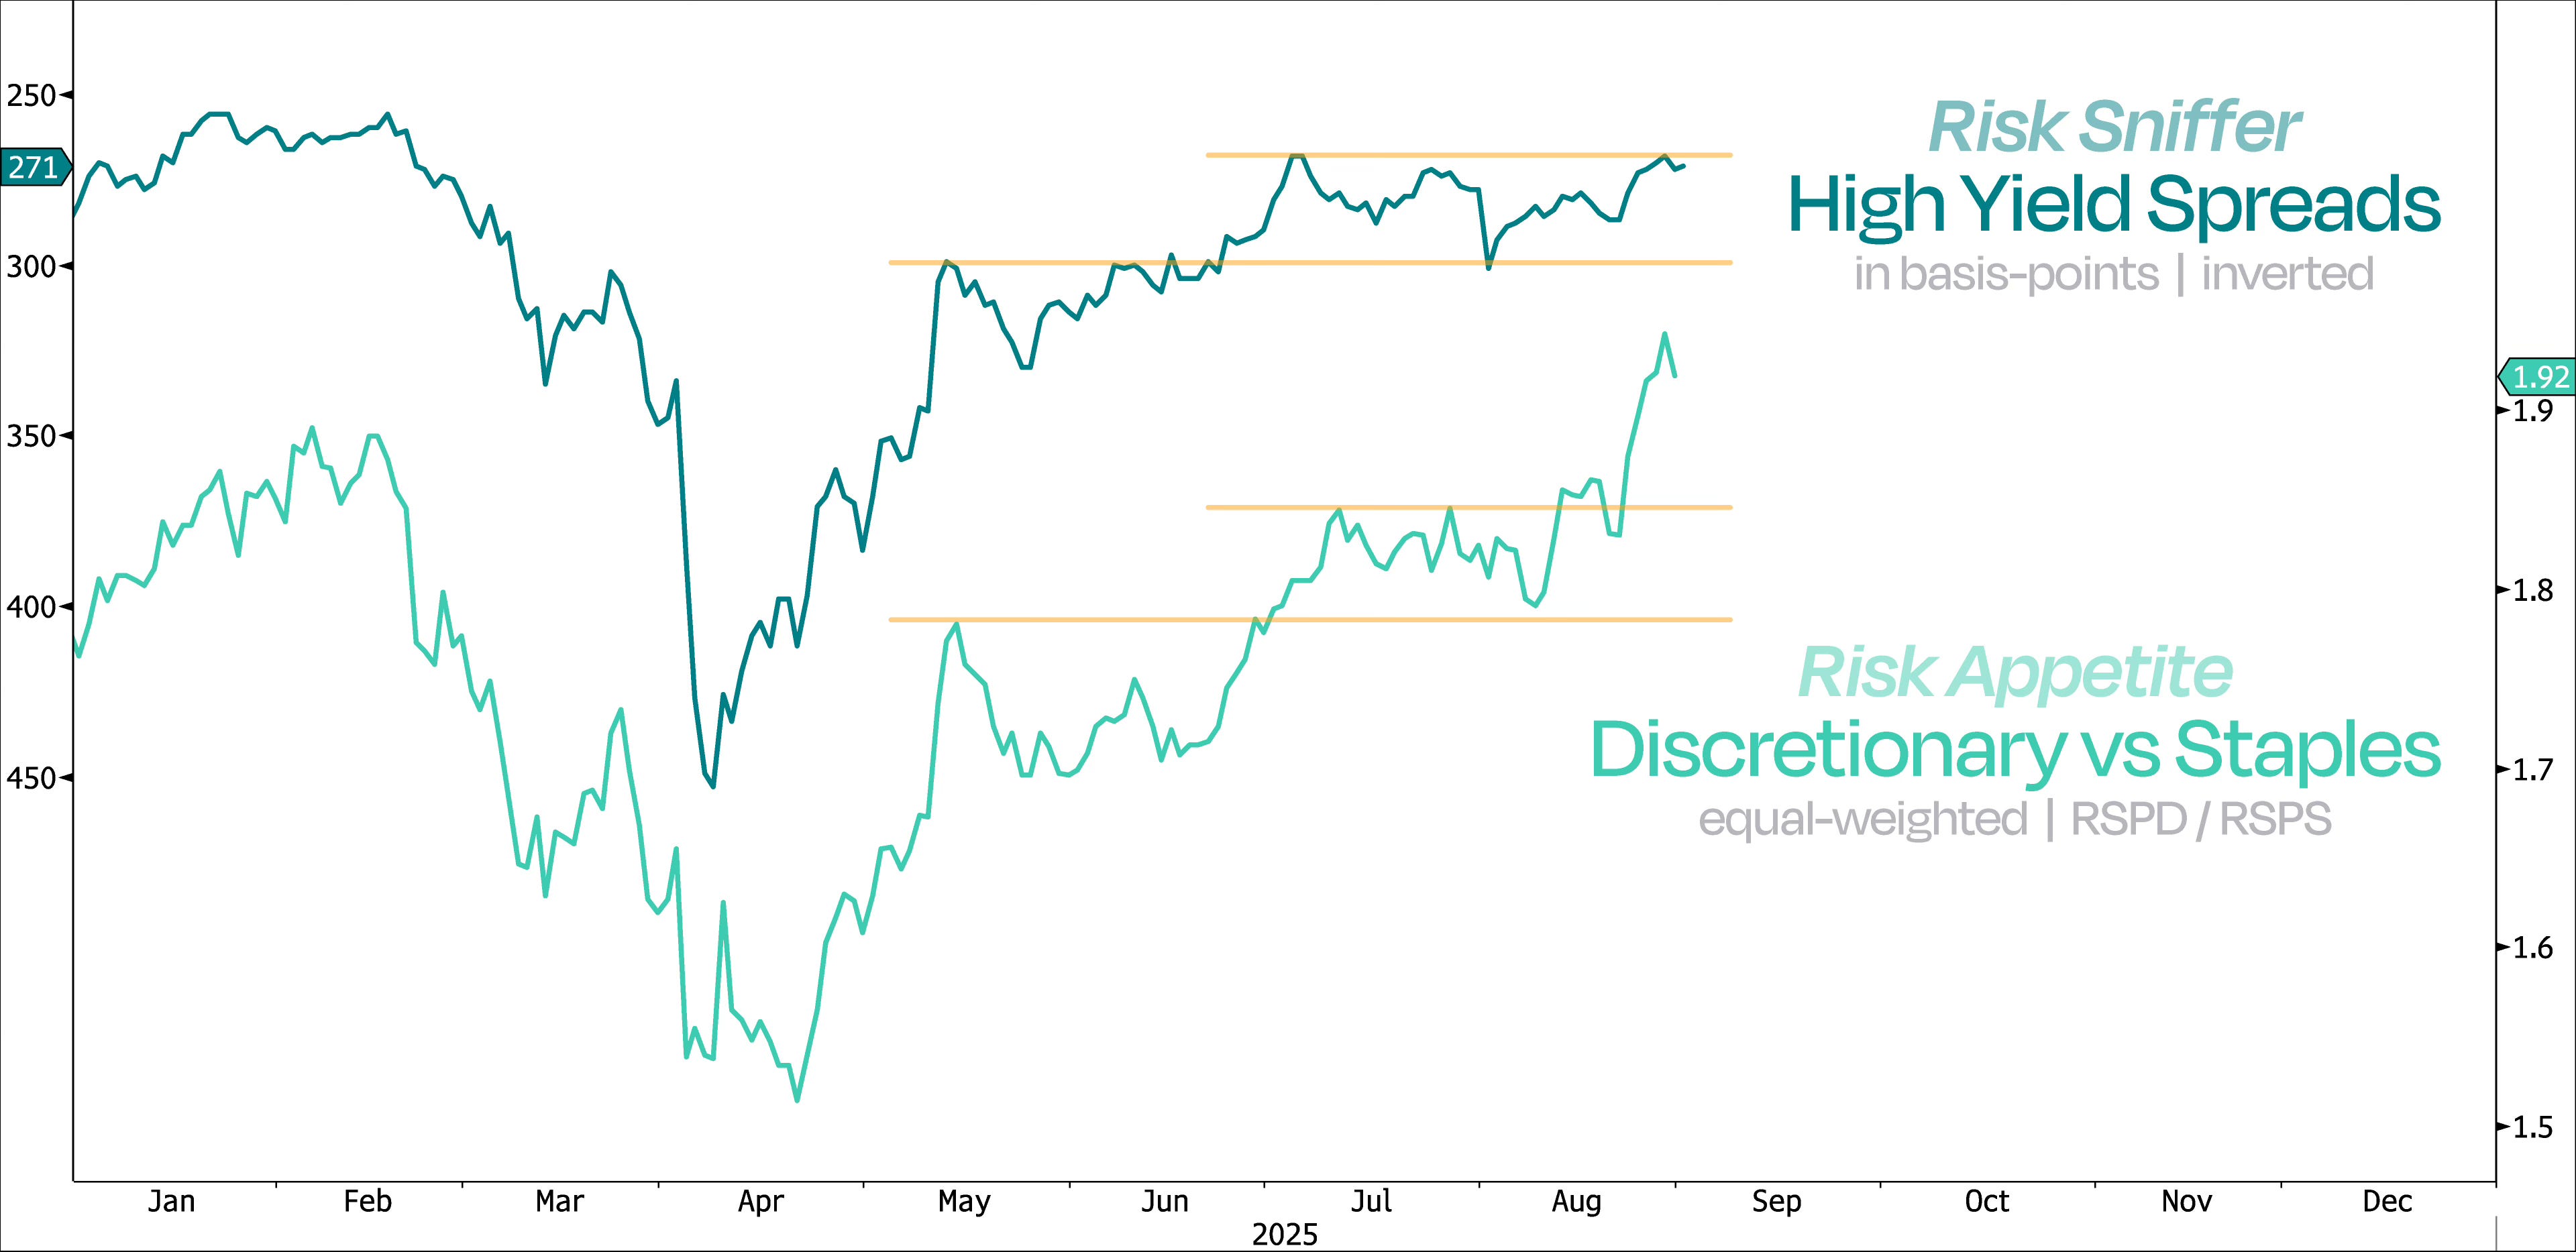
More often than not, widening credit spreads usually show up before stocks start sliding. And most of the time, it’s high-yield investors who start waving the red flag once their confidence in growth and defaults begins to fade.
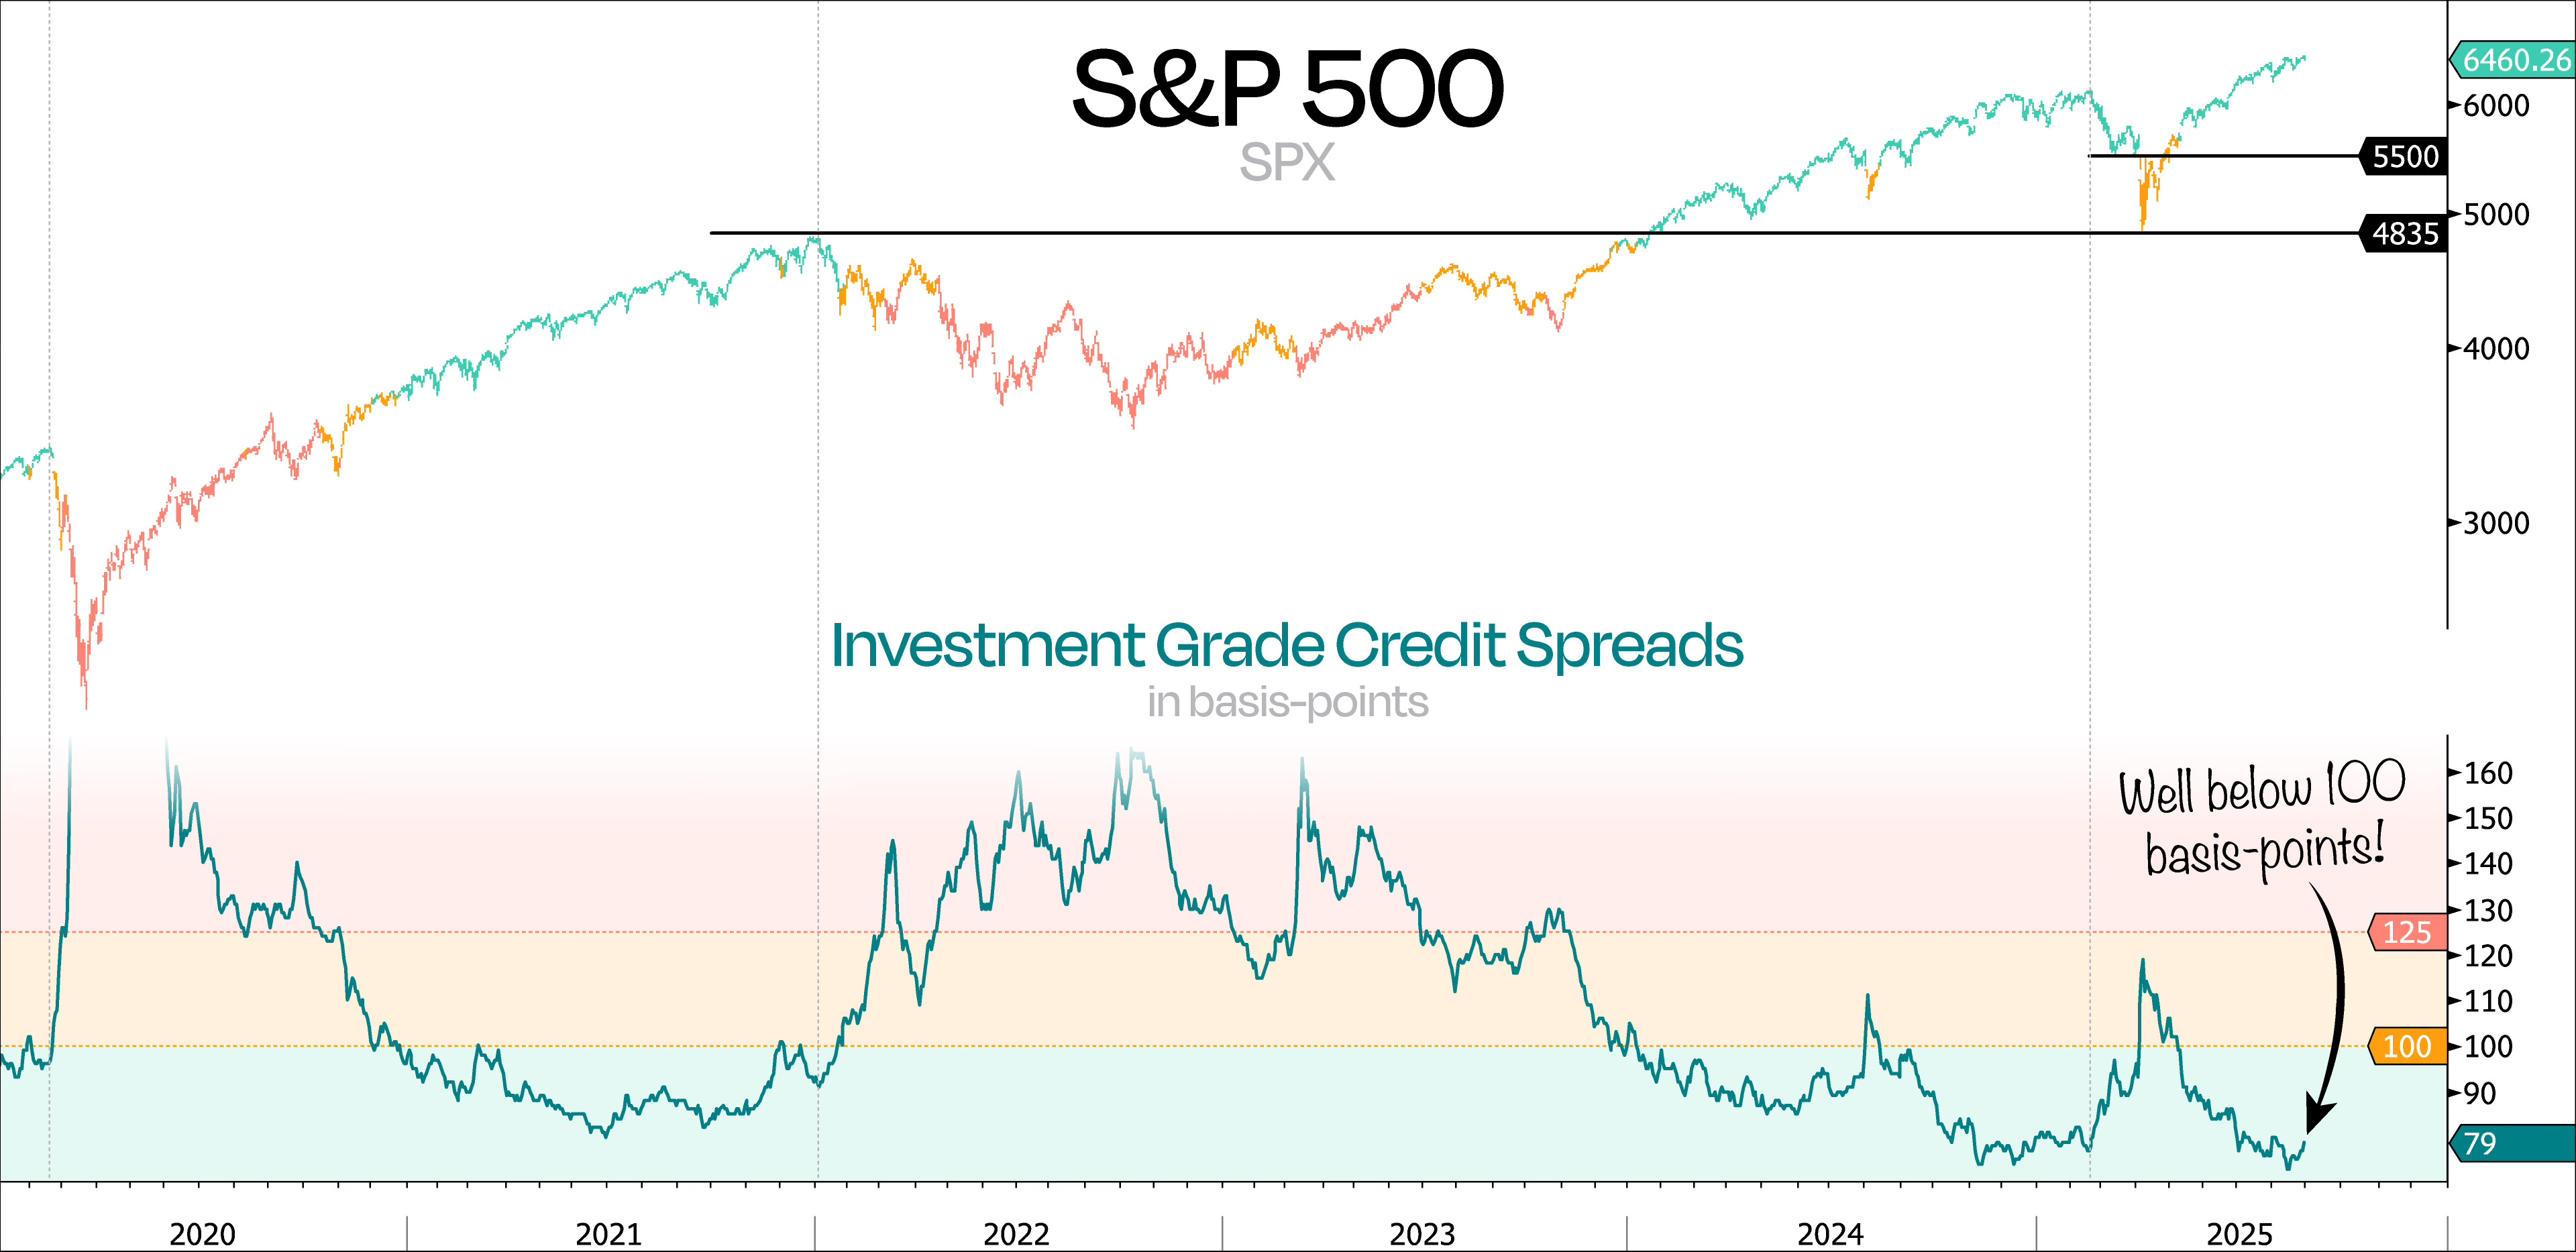
But since most S&P 500 companies are investment grade — even though the dividing line is still credit quality, not size itself — we like to keep a close eye on those too. Here, we usually like to say that nothing really bad happens when investment grade spreads are below 100.
Our color-coded chart shows two ways investors might read this. Some investors will be happy to see we’re deep in the green — proof there’s no need to panic. Others will see it as a sign of dangerous complacency.
Now, since credit spreads usually widen before major market peaks — which isn’t happening right now — we see these tight spreads as a sign that the corporate bond market is feeling pretty confident about US growth, a view the latest earnings season backs up.
Lately, that renewed economic optimism has also been showing up in the yield curve. What’s interesting is that:
The steepening we’re seeing is a bull steepener
(short-term yields dropping faster than long-term yields).And it’s happening in a normal, not an inverted curve.
Now, a bull steepener almost always means the market is betting on rate cuts. But the shape of the curve — whether it’s inverted or normal — and its absolute level tell you what kind of story it’s really telling.
In the next chart, we show the yield curve twice — once shaded for steepeners, once for flatteners. The quick explainer table at the top outlines the general implications of each case, but as we said earlier, whether the curve is normal or inverted adds an important layer of interpretation.
For example, during the extended bull steepening phase in the summer of 2024 — just before the Fed began cutting rates — the curve was still deeply inverted. That dynamic reflected markets pricing in a series of Fed cuts in response to economic weakness, with long-term confidence muted and recession fears elevated.
Today, however, the picture looks different. The bond market is again pricing in Fed easing, but this time without flashing an immediate recession signal. Growth is slowing, but it’s holding up ok, and the longer-term outlook looks a lot healthier than it did a year ago.
In other words, the bond market is telling us that cuts are mostly expected for the right reasons — primarily viewed as healthy, calibrated, and proactive adjustments rather than reactive measures.
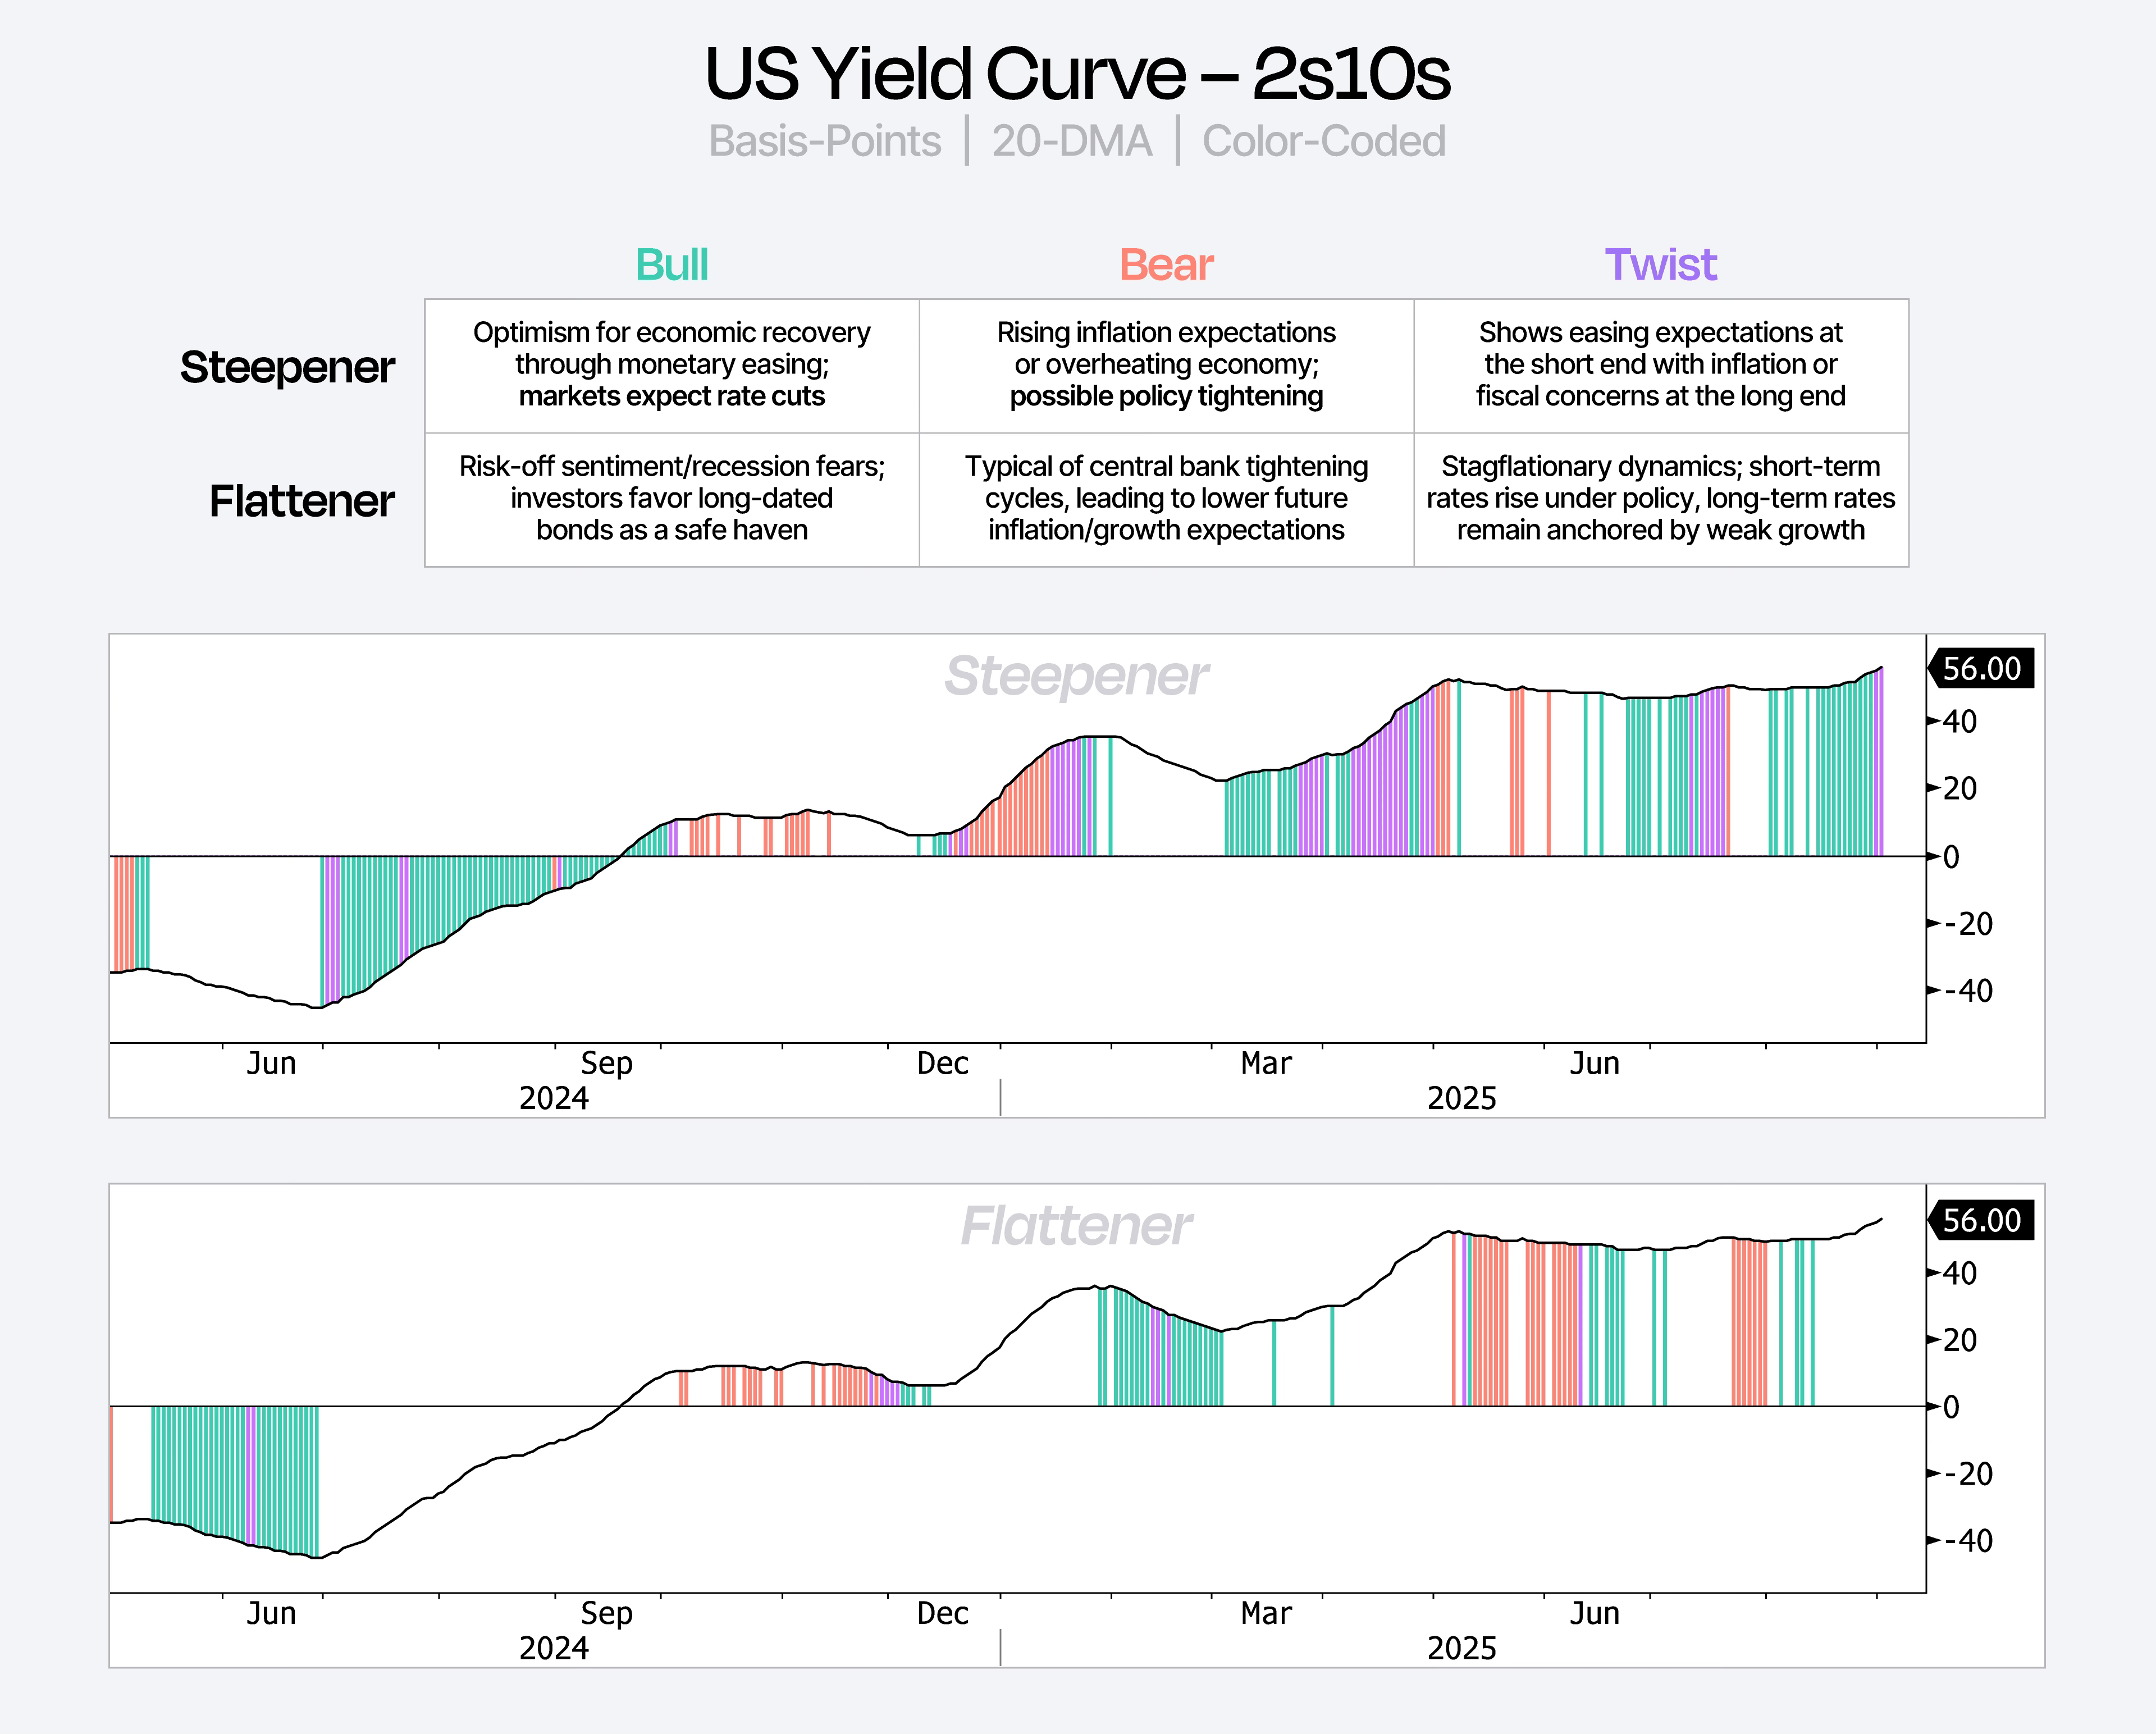
We wouldn’t be surprised to see this bull steepener morph into a drawn-out twist steepener — where short-term yields fall while long-term yields rise — suggesting markets are pricing in near-term easing at the front end while concerns about inflation and fiscal policy remain elevated at the long end.