

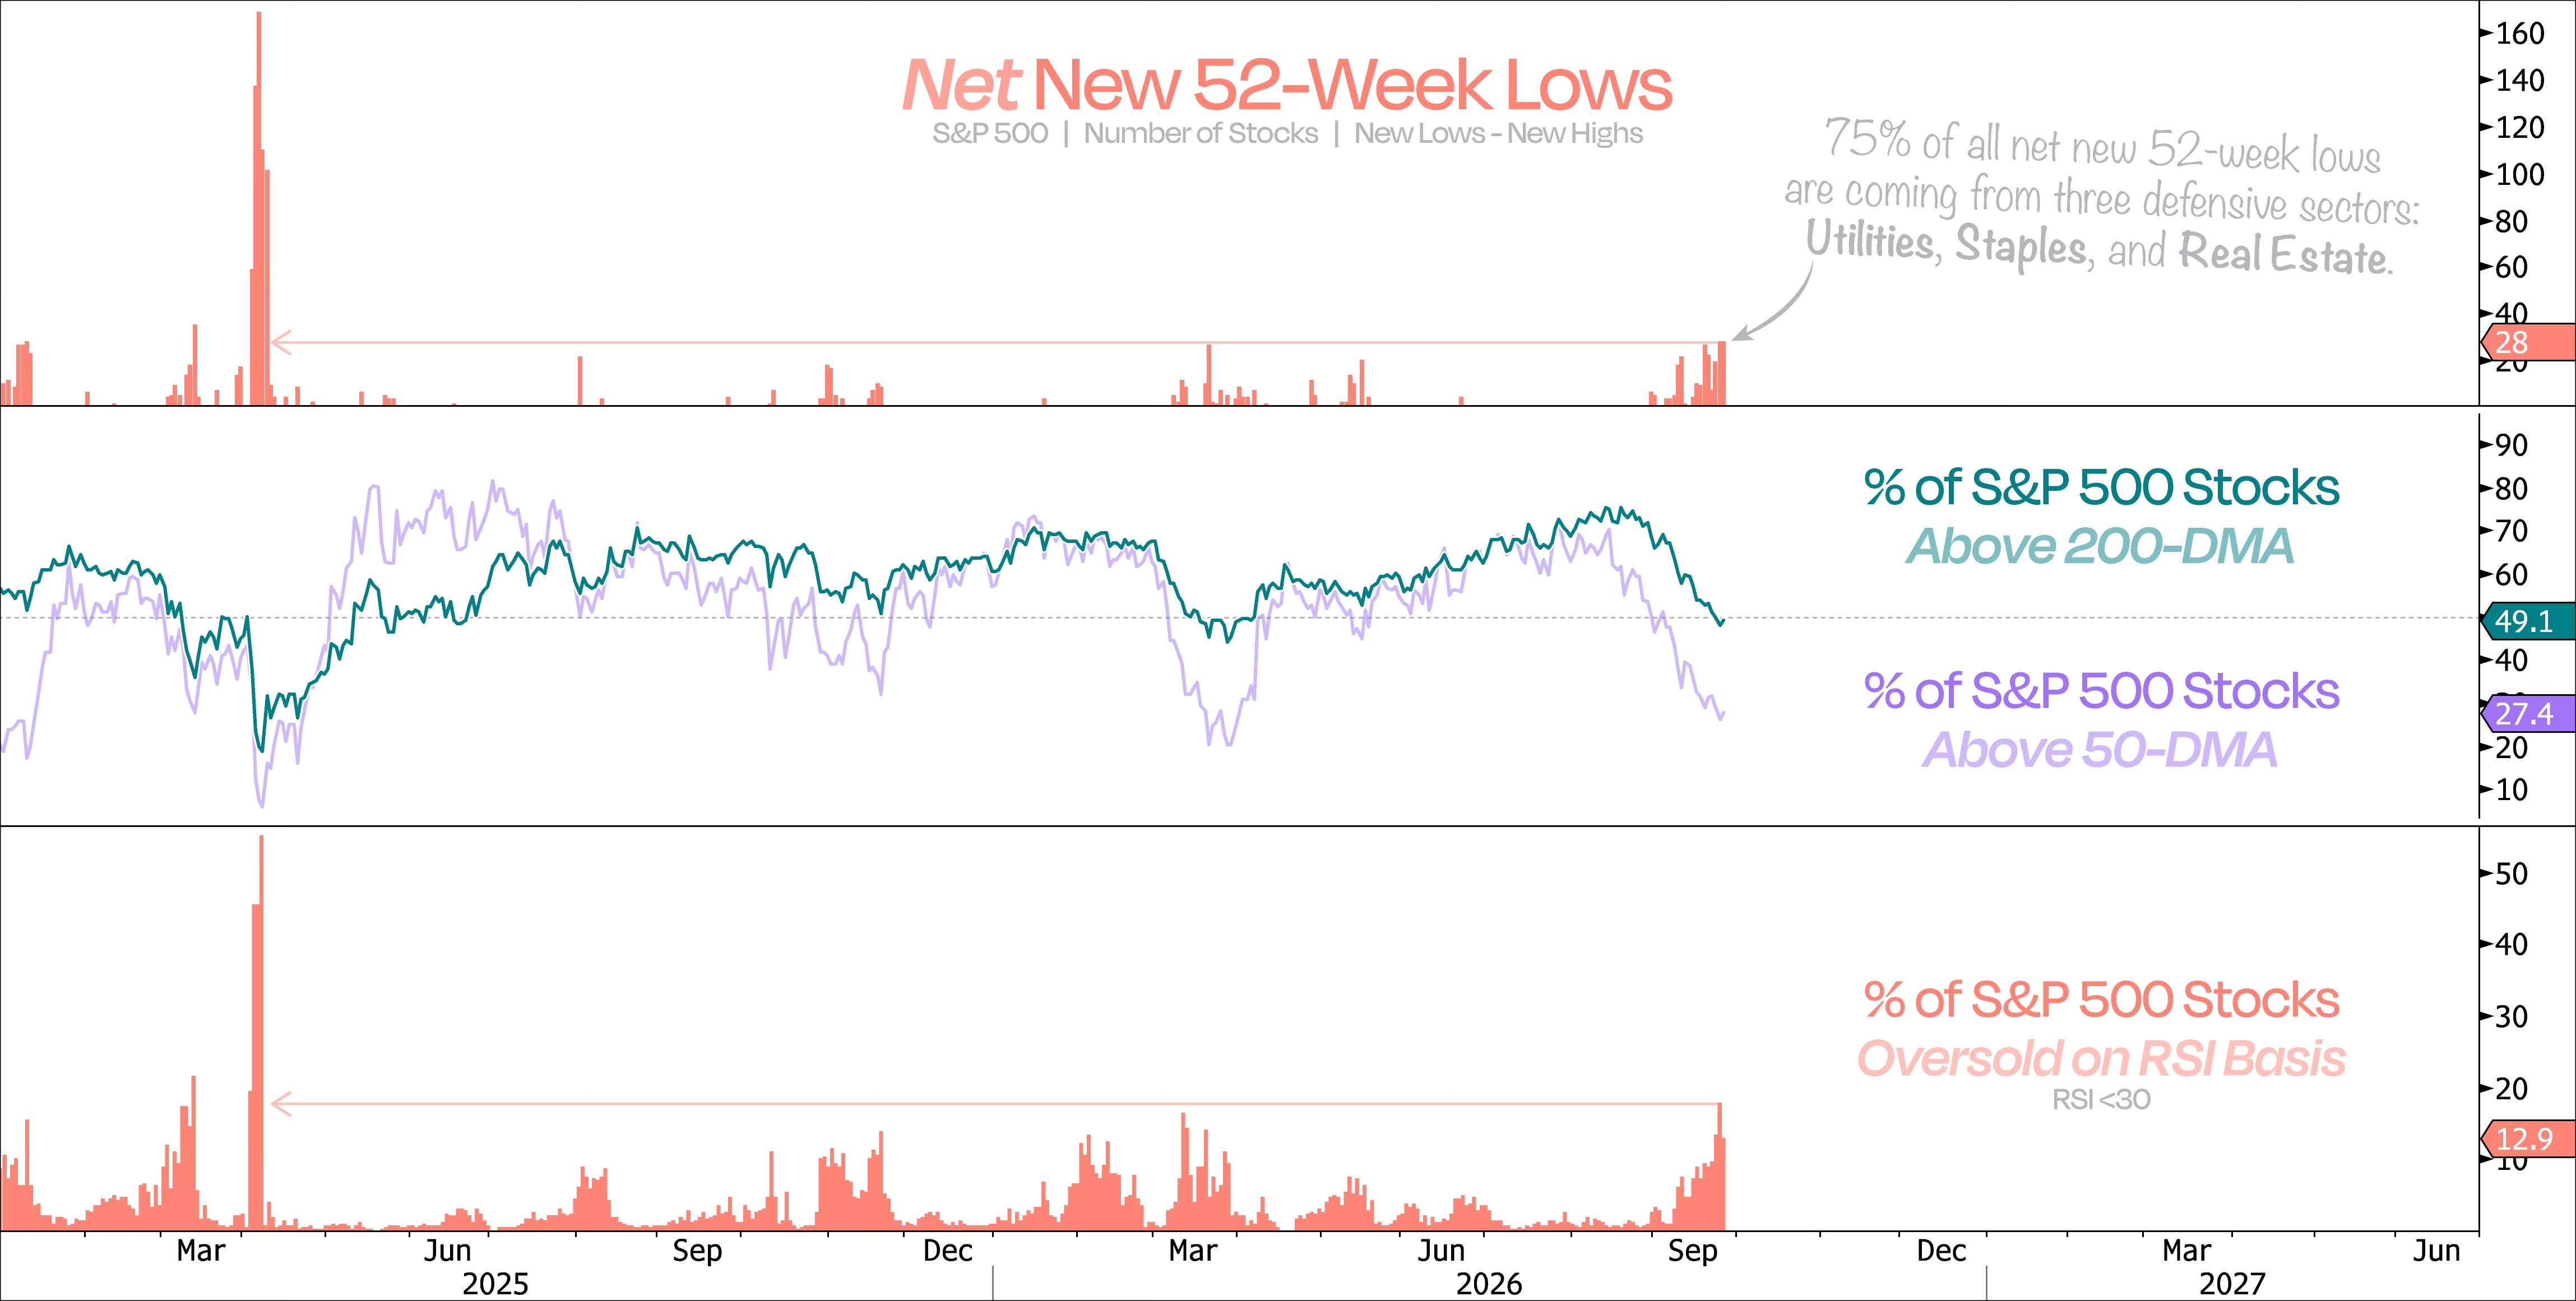
If you asked investors what happened last week, there’s a good chance many would point to some pretty ugly developments underneath the surface of the S&P 500:
The highest net new lows reading since April 2025
The most stocks reaching oversold conditions since April 2025
The percentage of stocks trading above their 50-DMA and 200-DMA continuing to decline
And, as a matter of fact, all of that did indeed happen last week.
Now, if you asked us what happened last week, we’d probably point to something very different.
Our Proprietary Risk Model simply continued to steadily improve, pushing even further into risk-on territory.
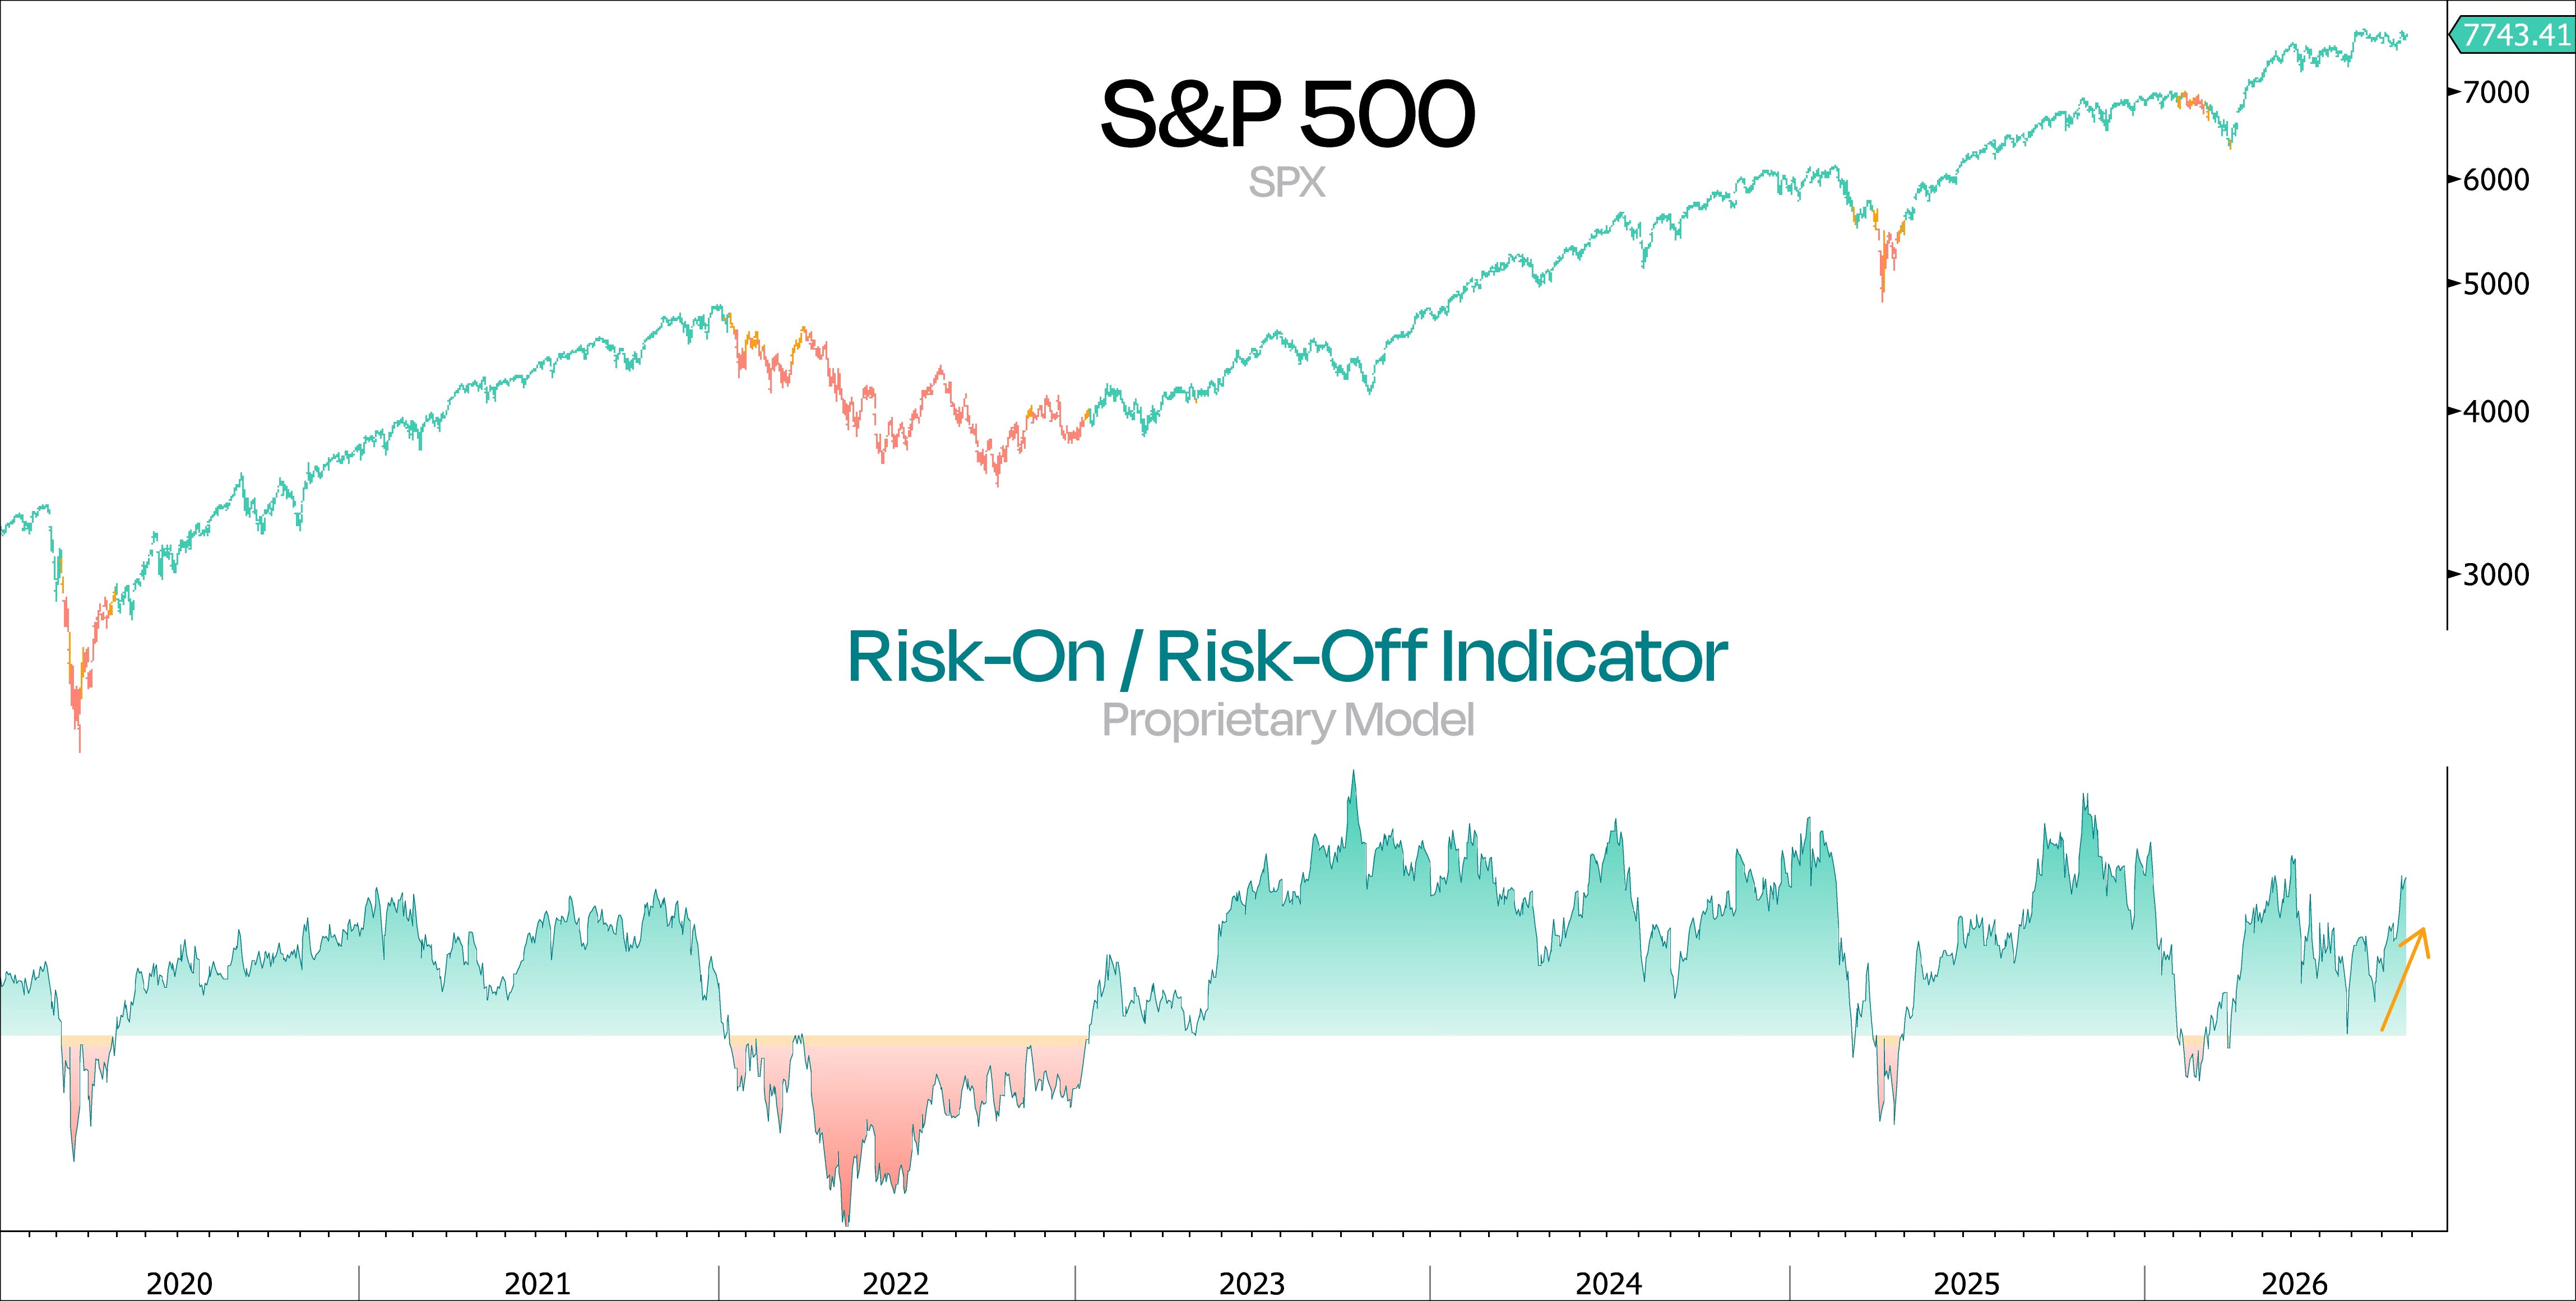
So why didn’t our Risk Model deteriorate alongside all that ugly breadth?
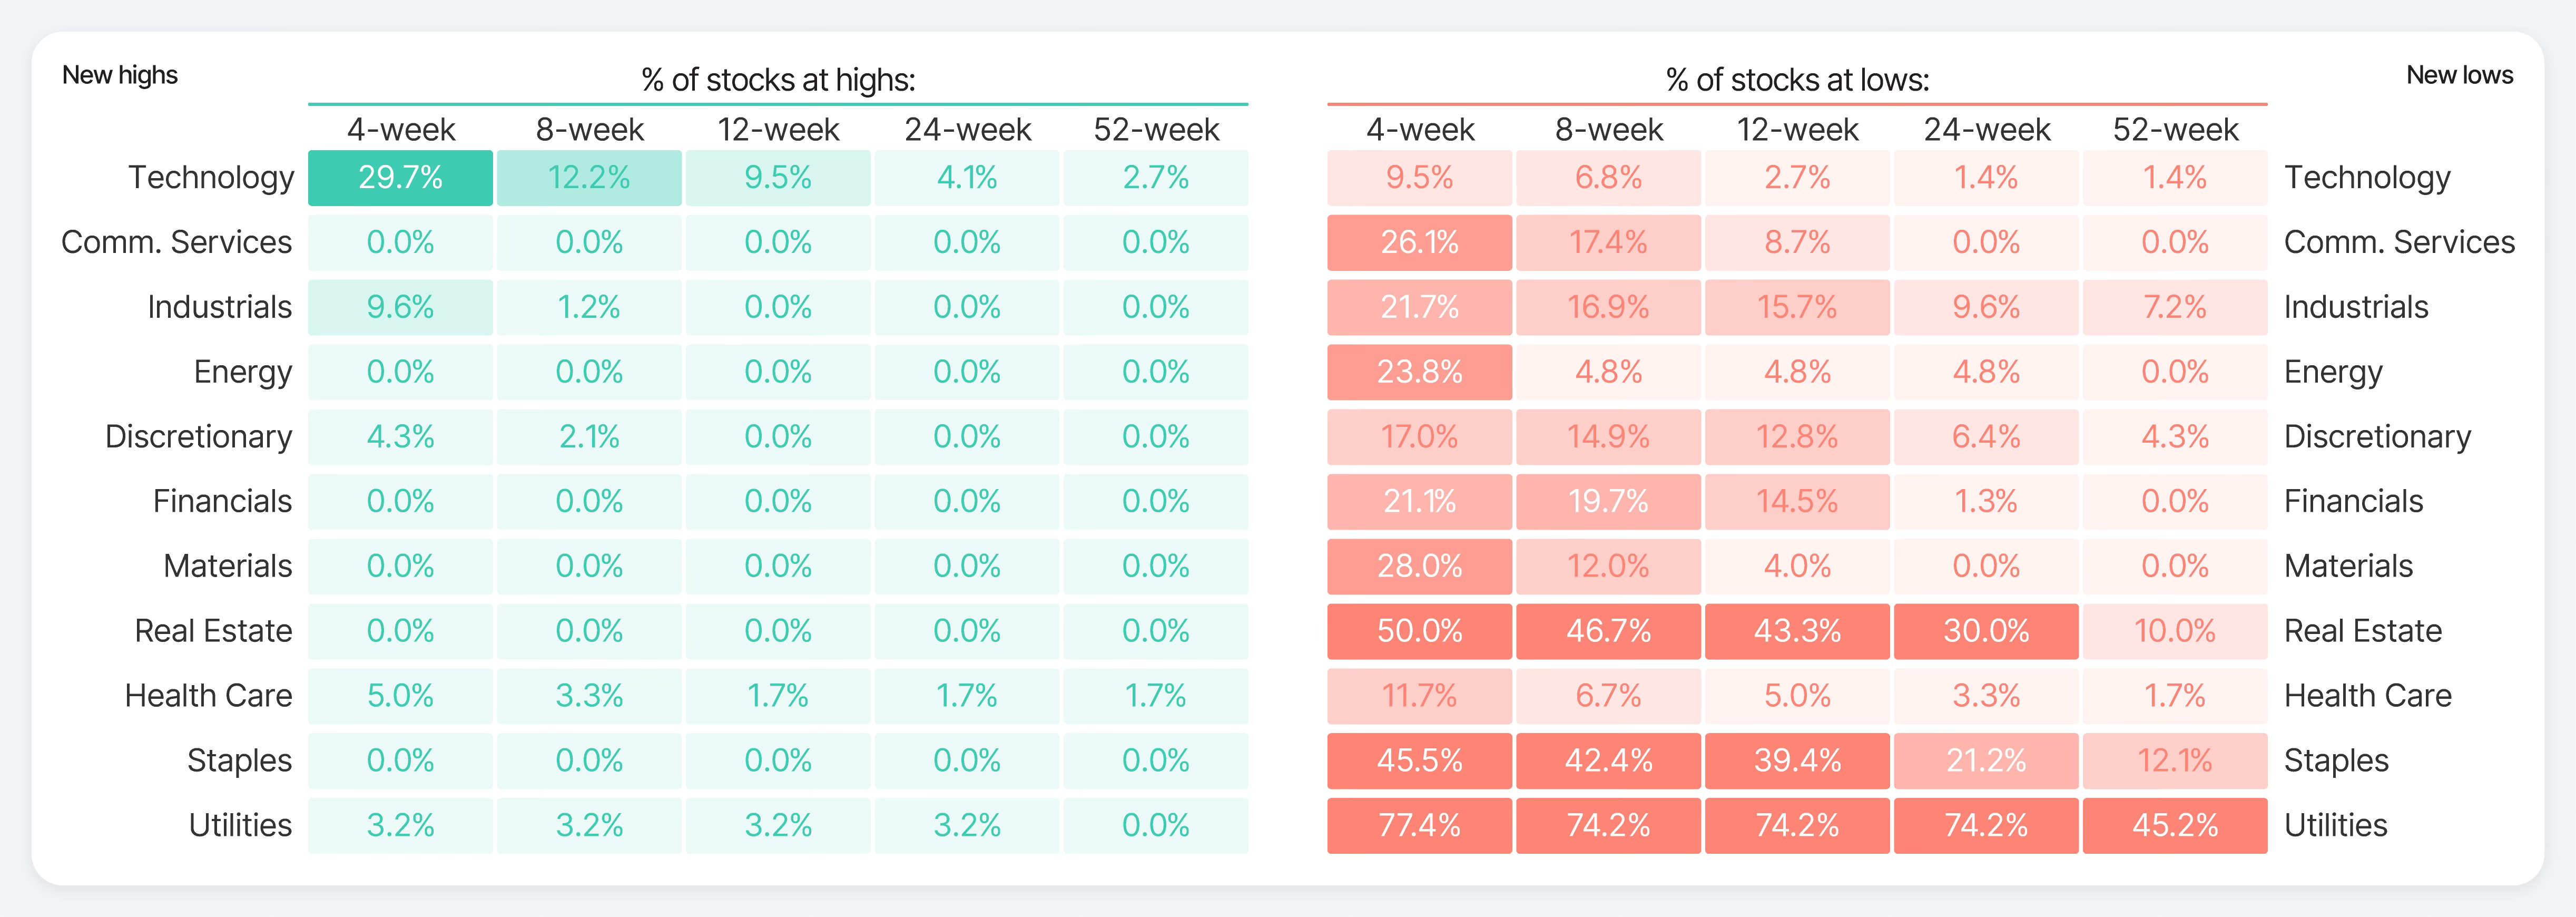
The simple answer is that once you look underneath the hood, things weren’t nearly as bad as the headline numbers suggested.
21 of the 28 net new lows came from Utilities, Staples, and Real Estate
Credit spreads remain tight
Several of our preferred risk-appetite ratios, including High-Beta vs Low-Volatility, pushed to new all-time highs
So yes, breadth stinks. But where it stinks matters. Or, as our friend Larry Thompson recently put it best: If breadth is bad, don’t own breadth!
And that’s basically exactly what we did last week. By entering our newest tactical trade, we effectively moved even further underweight breadth and overweight concentration. And so far, we’re pretty comfortable being on that side of the trade.
So today, we want to quickly leave you with two important things as we head into the new week: one that’s particularly relevant to our Bitcoin long, and another extremely bullish development that, interestingly enough, triggered on the very same day last week that we went overweight